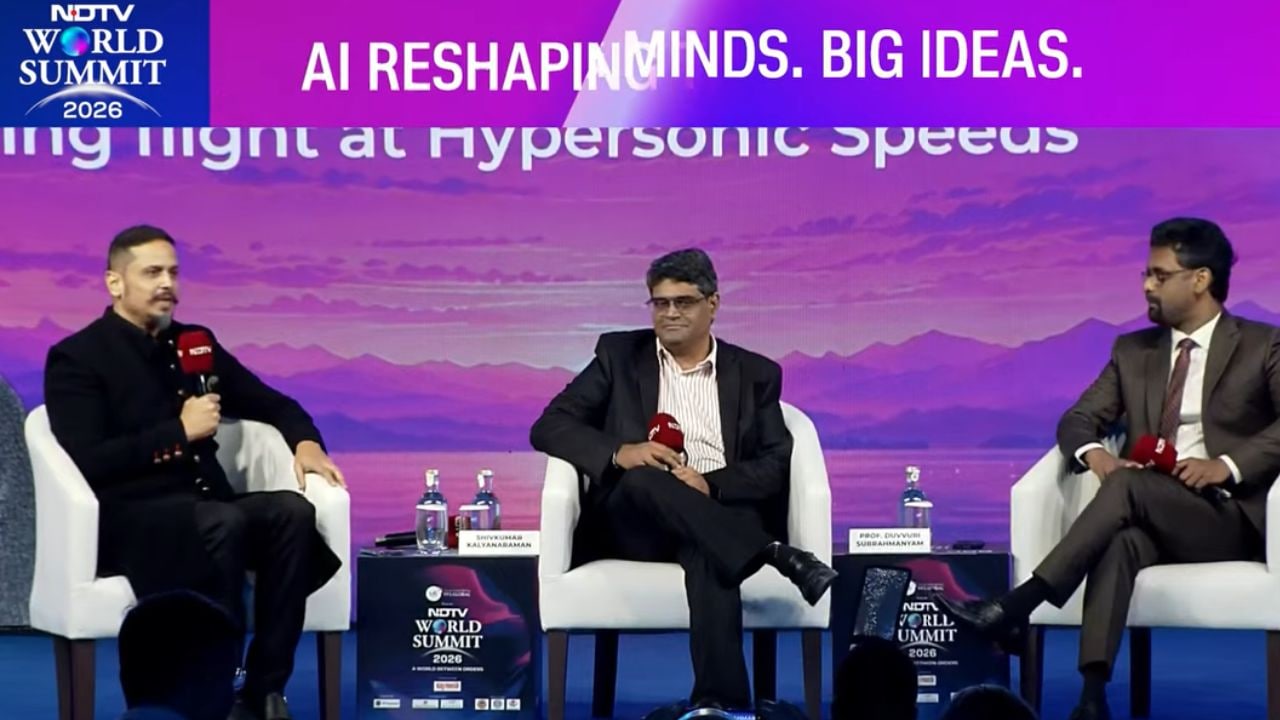
Treatment of India as a simple volume-consumption destination misreads the structural economics driving multinational expansion in 2026. When Pernod Ricard executive Prasanna Mohile addressed the NDTV World Summit in October 2026, his central claim was direct: global corporations must stop viewing India merely as a large consumer market and start treating it as a source of innovation, capabilities, and global influence. That argument captures a real strategic shift, yet summit coverage frequently stops at high-level optimism. Moving from a headline thesis to an operating playbook requires separating verified economic mechanics from aspirational framing, mapping cause-and-effect constraints, and defining where domestic capability building actually creates durable advantage.
Deconstructing the Summit Thesis and Its Missing Links
The argument presented at the summit rests on three interlocking claims: India ranks as Pernod Ricard's largest market by volume and second-largest by revenue; demand is shifting toward premium offerings; and local manufacturing plus supply chain localization anchor long-term value. Reported figures include an FTI Consulting study estimating roughly Rs 43,000 crore in total GDP contribution across direct, indirect, and induced channels, support for around nine lakh ecosystem jobs, and a multi-year plan to build a major malt manufacturing facility in Nagpur.
What summit summaries often compress is the causal chain connecting those inputs to enterprise returns. High volume alone does not guarantee margin expansion, especially in regulated consumer categories where state-level excise rules, distribution friction, and pricing tiers shape net realizations. Furthermore, multiplier estimates from economic impact studies aggregate direct operations, supplier spending, and induced household consumption; they measure macroeconomic footprint rather than net profit or capital efficiency.
A rigorous strategic analysis separates three categories of information:
- Verified operational facts: Pernod Ricard's volume and revenue ranking within the group, its reported full-year sales growth of 7% in India amid softer performance in other major markets, its announced Nagpur malt facility investment over the next decade, and the cited FTI Consulting GDP and employment estimates.
- Observable structural mechanisms: Shift in consumer mix toward higher-margin tiers ("affordable premiumisation" and smaller pack formats), localization of agricultural and packaging inputs to reduce import exposure and lead times, and deployment of domestic teams to build regional commercial and operational capabilities.
- Educated hypotheses: Whether localized malt and supply chain investments will compress unit landed costs enough to offset input inflation and state-by-state regulatory complexity over a ten-year horizon, and whether capabilities built in India can be exported into adjacent global markets without diluting brand equity.
The Three Pillars of Capability-Led Expansion
To translate a "beyond-a-market" thesis into execution, management teams need a concrete operating model rather than a slogan. In practice, multinational operators convert domestic scale into broader organizational strength across three functional pillars.
1. Supply Chain Localization as Margin and Lead-Time Defense
Importing core raw materials or finished goods exposes consumer businesses to currency swings, freight volatility, and tariff friction. Investing in domestic upstream capacity—such as malting infrastructure tied to regional agricultural sourcing—alters the cost structure in two ways. First, shortening physical supply loops reduces working capital tied up in transit and buffer inventory. Second, closer proximity to growers and packaging vendors creates room for agronomic quality standardization and local cost engineering.
The cause-and-effect chain is conditional rather than automatic. Local sourcing only lowers total cost of ownership if agricultural yields, storage quality, and processing scale match specification tolerances consistently. If local input prices spike during weather shocks or logistics bottlenecks, localized plants still face margin pressure.
2. Portfolio Architecture and Mix Shift Mechanics
Revenue growth in a large population base depends heavily on mix management rather than raw unit count alone. When consumers trade up within a category or adopt smaller formats at accessible price points, companies can test price-pack architecture at high frequency. In consumer goods, mix shift raises gross margin per liter or per unit when higher-tier SKUs grow faster than entry-level volume.
Yet mix shift carries an operational trap: SKU proliferation increases complexity across bottling, warehousing, and retail execution. A disciplined operator pairs premiumization with portfolio pruning, ensuring new formats and higher-tier expressions earn shelf velocity instead of cannibalizing core lines or inflating inventory write-offs.
3. Capability Export and Organizational Gravity
Treating India as a source of capabilities means building repeatable competencies—such as digital commerce execution, localized route-to-market analytics, cost-disciplined manufacturing engineering, or regional leadership talent—that solve problems relevant elsewhere. When headquarters in mature markets face sluggish growth or high operating costs, proven playbooks from high-growth, cost-sensitive markets can inform global resource allocation.
Even so, capability transfer requires deliberate governance. A commercial model tuned to one regulatory and retail environment cannot be copy-pasted blindly into another market with different tax structures, consumer habits, or channel power. Capability becomes global influence only when teams extract underlying principles rather than surface tactics.
Step-by-Step Operating Playbook for Multinational Leaders
Executives testing whether India should serve as a capability engine for their organization can follow a five-step sequence:
- Audit true unit economics by channel and state or region. Separate headline volume growth from net contribution after excise, trade discounts, freight, and promotional spend.
- Map upstream bottlenecks before committing heavy capital. Identify where imported inputs, packaging, or third-party processing create lead-time risk or margin leakage, then size local investments like agricultural processing plants to match realistic demand curves.
- Rationalize the SKU ladder around clear price-pack roles. Define which products drive trial and volume, which drive repeat frequency, and which expand unit margin, retiring low-velocity variants that clog distribution.
- Codify operational playbooks with measurable transfer criteria. Document process improvements—from plant efficiency to route-to-market execution—and test them in one comparable market before scaling globally.
- Track ecosystem value alongside financial return. Monitor supplier stability, workforce development, and local community impact as license-to-operate metrics, while keeping board reporting anchored to return on invested capital and free cash flow.
Why Standard Metrics Misread This Shift
Conventional market-entry scorecards rely heavily on population size, per-capita consumption, and short-term top-line growth. Those metrics answer a narrow question: how big can demand get? They fail to answer whether a company is building defensible operational assets or merely renting growth through heavy commercial spending.
A sharper diagnostic looks at three friction points that often derail multinational ambitions:
- Regulatory fragmentation: Where rules, licensing, or taxation vary sharply across sub-national jurisdictions, national scale averages can mask local compliance costs and approval delays.
- Margin vs. volume divergence: Rapid volume expansion in lower-priced tiers can flatter market-share charts while depressing operating margins if fixed overhead scales faster than net revenue.
- Long payback horizons: Upstream manufacturing and ecosystem investments require multi-year patience; quarterly earnings pressure can tempt managers to underinvest in foundational infrastructure.
Strategic Play for the Next Cycle
Treat India as a dual-engine testbed—using domestic demand to fund disciplined mix upgrade while using local supply chain and operational execution to stress-test cost resilience for global deployment. Commit capital to upstream localization only where clear input or lead-time advantages exist, enforce strict SKU discipline so premiumization expands margins rather than complexity, and judge success by durable return on invested capital rather than headline scale alone.
Pernod Ricard India head at NDTV World Summit 2026
This video features Prasanna Mohile's address at the NDTV World Summit 2026 on India's economic resilience, domestic capabilities, and long-term growth role for global businesses.