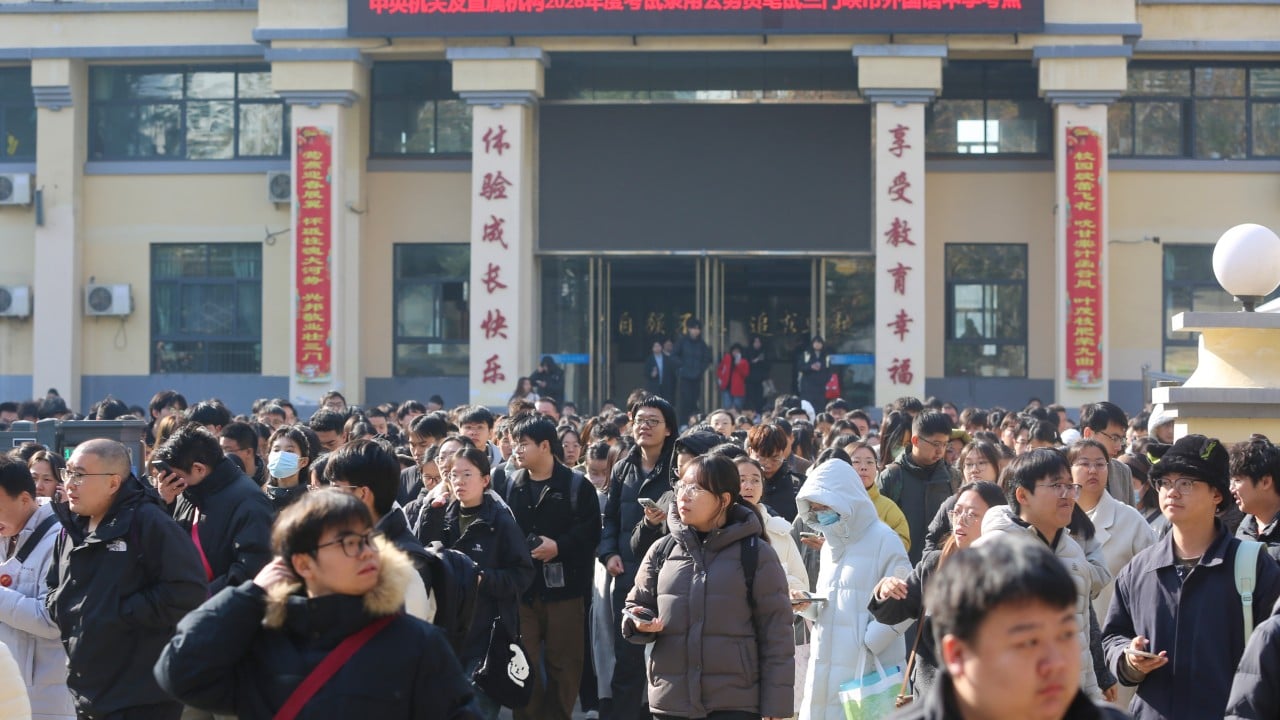
China just put over 24,000 tax roles on its 2027 civil service hiring slate, making up more than two-thirds of all openings. That number stopped me cold. When a government hires collectors at that scale while rolling out smarter audit software, it isn't just housekeeping. It's a pressure valve releasing where old revenue engines stalled.
For years, local governments leaned on land sales to fund roads, schools, and daily operations. Property slowed down, land-use-right transfer receipts dropped sharply, and municipal budgets felt the squeeze. At the same time, Beijing has been building out data-driven tax monitoring and pushing harder on compliance across listed firms, export chains, platform businesses, and offshore wealth.
Hiring thousands of tax officials doesn't replace algorithms. Honestly, it proves the exact opposite. Software can flag an odd return in milliseconds, yet someone still has to review files, issue queries, handle cross-border cases, and chase down unpaid bills.
Why China Expands Tax Workforce Right Now
When you look at China expands tax workforce stories in isolation, they can sound like a routine staffing bump. Put them next to fiscal math and they read like necessity. Land-use-right revenue fell 14.7% in 2025 and slid another 28.6% year over year from January through August 2026. Meanwhile, overall tax revenue rose 6.6% and personal income tax receipts jumped 14.5% to 1.208 trillion yuan over that same stretch.
Fiscal pressure doesn't automatically create a crackdown by itself, though. You need both motive and leverage. Over the past couple of years, authorities have combined cross-department inspections, big-data analytics, and international information sharing to spot gaps that used to slip through. More staff gives bureaus the human bandwidth to follow up when systems spot a mismatch.
There's also a structural angle many observers miss. During the 2026 National Tax Work Conference, officials pointed toward deeper audits of major cases handled at higher levels to curb local interference, while drawing a clearer line between honest mistakes and deliberate evasion. Bigger teams make that kind of centralized follow-through possible.
What Algorithms Catch And What Humans Still Do
People love to picture tax enforcement as a cold wall of code that catches every discrepancy on its own. That's only half true. Automated systems under Golden Tax Phase IV and related digital tools can spot statistical outliers—like a company filing zero revenue while money moves through bank accounts, or payroll numbers that clash with social insurance bases.
Real-world cases still require judgment. Auditors have to verify whether a cross-border transaction has commercial substance, check supply-chain invoices against real goods, and sort out genuine accounting errors from intentional underreporting. Let's be real: a database can wave a yellow flag, but a person has to read the contracts and explain the finding in a formal notice.
Four Pressure Points Driving Tougher Enforcement
Enforcement isn't hitting every taxpayer the same way. Looking at recent enforcement trends and reported cases, four areas stand out where scrutiny has sharpened noticeably.
- Export rebates and supply chains: Authorities have targeted fake invoicing, shell intermediaries, and full-chain fabrication used to claim export tax rebates improperly, alongside evasion tied to high-emission or resource-intensive exports. If you buy goods through third-party agents or unverified suppliers without clean documentation, a broken link upstream can pull your records into the light.
- Platform and digital activity: Rules requiring internet platforms to report tax-related information have closed plenty of informal loopholes. Sellers who treated online storefronts or side income as untraceable cash flows face much tighter data matching.
- Listed companies and core sectors: At least 80 listed firms were ordered to repay taxes and fees in 2026, with heightened attention on sectors such as pharmaceuticals, chemicals, and information technology. Big names get watched closely because their scale makes compliance signals visible across whole industries.
- Overseas income and cross-border structures: Chinese tax residents have long been subject to worldwide income rules under the Individual Income Tax Law, yet enforcement around foreign accounts, trusts, and offshore arrangements used to feel uneven. With international data exchange expanding—including updates around CRS 2.0 and CARF—unreported overseas income is harder to leave parked in the shadows.
The Hidden Friction Nobody Talks About Enough
Here's the catch that rarely gets enough air time: paper wealth and liquid cash don't always move together. A founder or high earner can hold millions or billions on paper in company equity or illiquid assets and still face a cash crunch when an assessment lands.
When that happens, people end up selling shares, taking on loans against assets, or pressing companies for dividends. A personal tax bill can ripple right into corporate governance and market pricing.
There's also a delicate balance for policymakers. Push too hard or too bluntly, and capital or talent might hesitate to commit. Push too softly, and public finances stay strained while compliant taxpayers resent those who cut corners. That tension is why officials emphasize distinguishing bona fide errors from willful evasion and encouraging pre-audit self-correction.
Common Mistakes Businesses Make When Rules Tighten
In my experience watching companies react to tougher tax oversight anywhere in the world, the biggest stumbles come from panicking late or guessing blindly. Three mistakes show up over and over.
- Treating compliance as a once-a-year scramble: Waiting until filing season to reconcile invoices, payroll, social insurance, and R&D records leaves finance teams rushing and guessing. Continuous data checks reward clean habits kept up month by month.
- Relying on "gray area" workarounds: Using personal accounts for business receipts, leaving shareholder loans unexamined, or glossing over unbilled wholesale purchases might have felt manageable in the past. Today, mismatched numbers stand out like a neon sign.
- Ignoring supplier and cross-border links: Even if your own books look tidy on the surface, sloppy transfer pricing files, weak documentation for preferential tax claims, or risky counterparties can trigger questions you aren't ready to answer.
One caveat worth keeping in mind: public enforcement reports highlight high-profile cases and aggregate trends, which can make every routine filing feel like an audit trigger. Not every discrepancy is fraud, and reputable advisors stress verifying actual facts and rules rather than reacting to rumors. For current policy updates and compliance context, resources like China Briefing and Acclime China offer useful ongoing coverage.
Practical Steps To Tighten Your Position Now
If you run a business, manage cross-border operations, or have personal income across jurisdictions tied to China, don't wait for a formal notice to test your records. Start with a plain-eyed check of how your numbers line up across systems.
- Reconcile core records first: Match your declared payroll, social insurance contributions, bank flows, and invoices so there are no unexplained gaps waiting to be questioned.
- Back up preferential claims and cross-border deals: Make sure R&D records, export rebate files, transfer pricing support, and overseas income disclosures are organized and accurate before anyone asks.
- Fix small mismatches early: When authorities leave room for self-correction ahead of formal audits, catching and resolving an honest mistake early is almost always cleaner and cheaper than fighting it later.